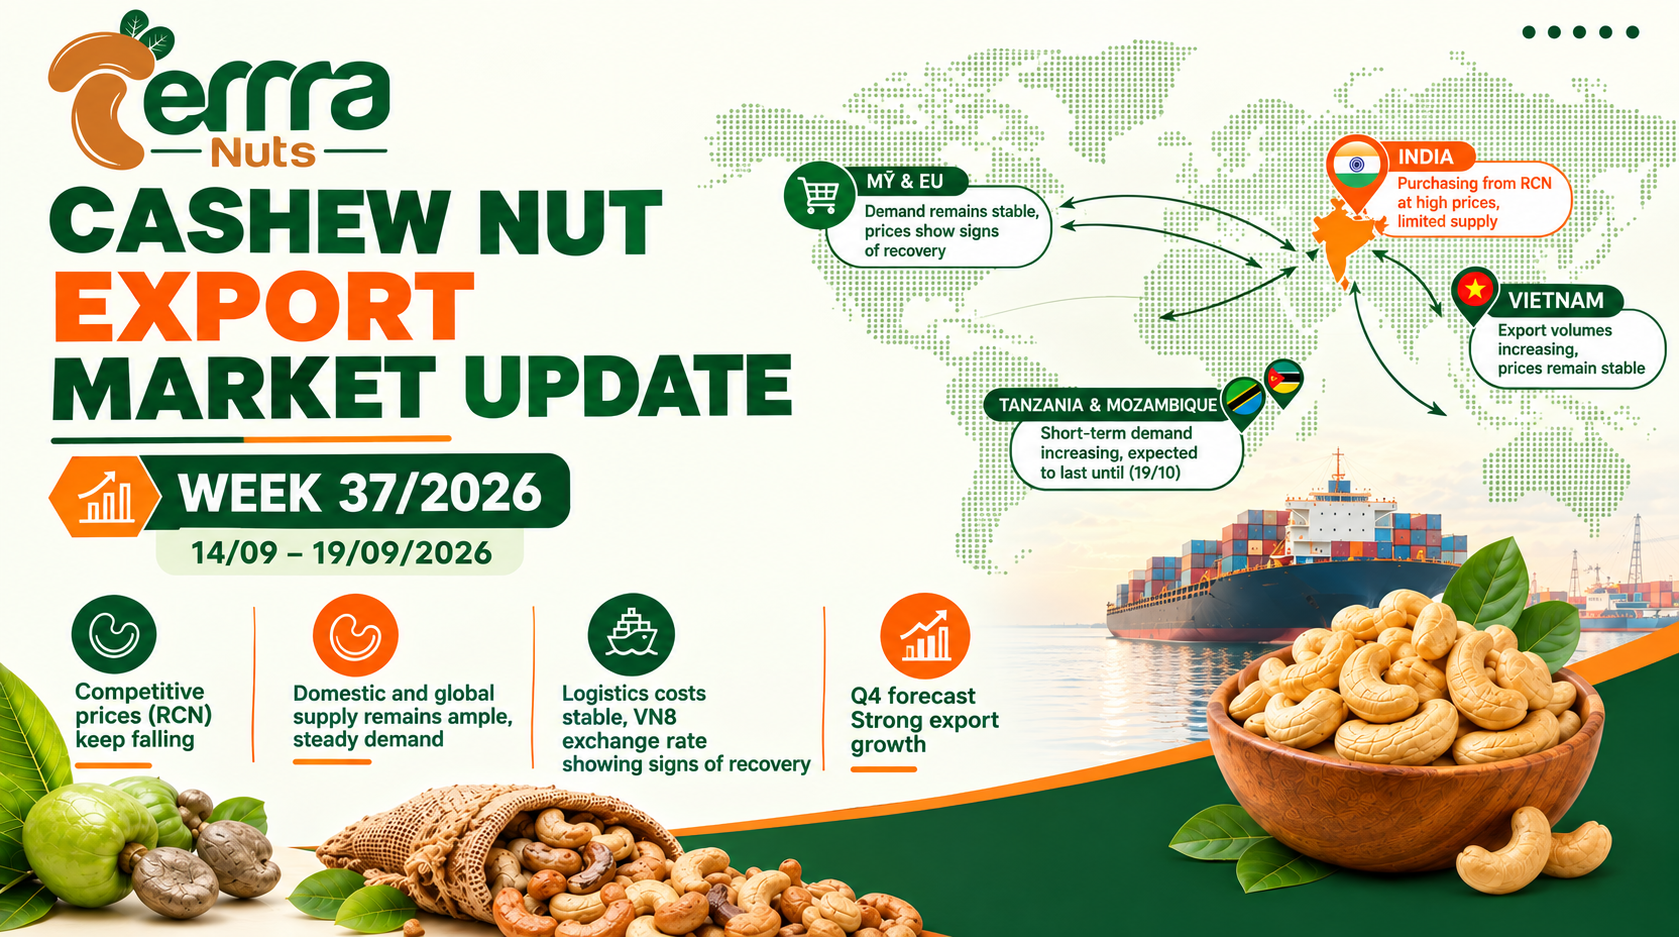
CASHEW MARKET REPORT – WEEK 37 (SEP 14 – SEP 19, 2026)
*ENGLISH VERSION
CASHEW MARKET REPORT – WEEK 37 (SEP 14 – SEP 19, 2026)
1. VIETNAM & INTERNATIONAL MARKET OVERVIEW
General Trends
The global cashew kernel market remains subdued. Buying interest continues to be scattered, with buyers maintaining a cautious stance and remaining unwilling to accept higher price levels.
Raw Cashew Nut (RCN) prices remain high, whereas cashew kernel prices have not increased proportionately, leading to sluggish trading activity. Many RCN traders still expect kernel prices to rise and have thus withheld price cuts.
The market is supported by steady demand from the US, EU, and the Middle East, alongside high RCN replacement costs.
In Tanzania and Mozambique, weather conditions are generally favorable for the 2026/27 crop. Tanzania is expected to commence new-crop auctions on October 19, 2026, targeting a total production of 750,000 metric tons of RCN.
Vietnam Cashew Kernel Export Prices (FOB)
W320: Traded mainly around 3.10–3.15 USD/lb; premium-quality suppliers are offering at 3.20–3.30 USD/lb.
W240: Ranging around 3.50–3.55 USD/lb. Elevated price levels are curtailing demand in certain markets such as Turkey.
WS: Stable around 2.67 USD/lb.
LP: Slightly increased to approximately 2.08 USD/lb.
Supply of broken cashew grades from Vietnam remains relatively constrained, whereas West Africa still holds fairly abundant inventory.
Supply & Demand Dynamics
Overall kernel demand remains weak, with importers buying strictly on a short-term, hand-to-mouth basis.
Global RCN supply is expected to improve from Tanzania and Mozambique thanks to favorable weather conditions.
High raw material costs continue to underpin kernel prices, despite final consumer demand not showing strong momentum.
2. RAW CASHEW NUT (RCN) MARKET
RCN Prices Firmly Maintained
The RCN market is relatively quiet, yet prices remain firm at elevated levels.
Buyers show little enthusiasm as current RCN prices do not align with the profitability of cashew processing operations.
Many suppliers and traders continue to hold stock in anticipation of higher finished kernel prices in the coming period.
Reference RCN Prices (CNF Vietnam)
| Origin | Quality (Nut Count / KOR) | CNF HCM Price (USD/MT) |
| Indonesia | 52/200 | 1,840 |
| Ivory Coast | 45/185 | 1,540 |
| Ghana | 42/200 | 1,400 |
3. VIETNAM CASHEW IMPORT & EXPORT
Cashew Kernel Exports
In the first 8 months of 2026, Vietnam exported 477,894 metric tons of cashew kernels, a slight decrease of 0.89% year-on-year compared to 2025.
Export turnover reached approximately USD 3.37 billion, up by 2.85%.
The average export price reached around USD 7,061 per metric ton, representing a 3.77% increase.
Notable Markets
China remains the largest export destination with 115,312 metric tons, up 6%.
The United States ranks second with 102,947 metric tons, up 8%.
Markets showing strong growth include Israel (+28%), Canada (+26%), Spain (+16%), and Australia (+4%).
The Middle Eastern market weakened sharply, with exports to the UAE dropping by 79% and Saudi Arabia falling by 28%.
Raw Cashew Nut Imports
Vietnam imported 2.12 million metric tons of RCN in the first 8 months of 2026, down 2.29% compared to the same period in 2025.
Import value rose by 5.69%, driven by an increase in the average import price to USD 1,658 per metric ton (+8.17% YoY).
RCN Imports by Origin
- Cambodia: 1.017 million metric tons, up ~10%, accounting for nearly half of total imports.
- Ivory Coast: 360,105 metric tons, down 10.18%.
- Nigeria: 164,706 metric tons, down 21.85%.
- Tanzania: 165,352 metric tons, up 23%, marking the strongest growth among African suppliers.
- Ghana: 115,675 metric tons, showing a sharp decline.
4. INTERNATIONAL CASHEW KERNEL PRICES
Reference FOB Prices (As of Sep 14, 2026)
| Grade | Vietnam (USD/lb) | Africa (USD/lb) |
| W240 | 3.52 | 3.73 |
| W320 | 3.20 | 3.48 |
| WS | 2.67 | 2.73 |
| LP | 2.07 | 2.33 |
5. SHORT-TERM OUTLOOK
The cashew kernel market is likely to remain sluggish as buyers have yet to accept current asking prices.
Elevated RCN costs will continue to provide strong support, preventing kernel prices from dropping significantly.
The 2026/27 Tanzanian crop season starting October 19 will be a crucial factor shaping the RCN market direction in Q4 2026.
Weather conditions in Tanzania and Mozambique are currently favorable; however, late September to early October will be critical for fruit setting and final crop yield.
In India, a weaker Rupee and high RCN costs will continue to limit downside pressure on local kernel prices in the short term.
Kernel price levels are expected to remain stable in the coming weeks, but a major breakthrough is unlikely without fresh demand from key consuming markets.
Sources & Disclaimer
*Disclaimer: This report is provided for informational purposes only and does not constitute investment advice or trading guidance. Data, opinions, and forecasts are compiled from sources believed to be reliable at the time of publication, but absolute accuracy, completeness, or timeliness is not guaranteed. The publisher assumes no liability for any losses arising from the use of information contained in this report. Readers should exercise caution and consult professionals before making decisions.
CHINESE VERSION (中文版本)
腰果市场周报 – 第37周(2026年9月14日 – 9月19日)
1. 越南及国际市场概述
总体趋势
全球腰果仁市场持续沉寂。采购需求依然分散,买家保持谨慎观望态度,尚未准备接受更高的价格水平。
生腰果(RCN)价格维持高位,而腰果仁价格未能同步上涨,导致市场交易放缓。许多RCN贸易商仍预期果仁价格将上涨,因而未降低售价。
来自美国、欧盟和中东的稳定需求以及高企的RCN重置成本对市场形成支撑。
在坦桑尼亚和莫桑比克,天气条件总体有利于2026/27季作物生长。坦桑尼亚预计将于2026年10月19日开启新季拍卖,目标产量为75万吨RCN。
越南腰果仁出口交易价格(FOB)
W320:主要成交于3.10–3.15美元/磅;优质供应商报价为3.20–3.30美元/磅。
W240:约为3.50–3.55美元/磅。高价限制了土耳其等部分市场的需求。
WS:稳定在2.67美元/磅左右。
LP:微幅上涨至约2.08美元/磅。
越南碎腰果供应较为紧缺,而西非地区的库存相对充足。
供需趋势
腰果仁整体需求依然疲软,进口商仅按短期按需采购。
得益于良好的天气条件,坦桑尼亚和莫桑比克预计将改善全球RCN供应。
尽管终端消费需求未见强劲反弹,但高昂的原料成本继续支撑腰果仁价格。
2. 生腰果(RCN)市场
RCN价格坚挺
RCN市场相对平静,但价格依然维持在高位。
由于当前价格与腰果加工业的盈利能力不匹配,买家意愿不高。
许多供应商和贸易商因预期未来成品腰果仁价格上涨而继续囤货。
越南CNF参考RCN价格
| 产地 | 质量(粒数 / KOR) | 胡志明市CNF价格(美元/吨) |
| 印度尼西亚 | 52/200 | 1,840 |
| 科特迪瓦 | 45/185 | 1,540 |
| 加纳 | 42/200 | 1,400 |
3. 越南腰果进出口情况
腰果仁出口
2026年前8个月,越南出口腰果仁477,894吨,同比2025年微降0.89%。
出口额约达33.7亿美元,同比增长2.85%。
平均出口价格达约7,061美元/吨,同比增长3.77%。
重点市场
中国继续保持最大出口市场地位,出口量达115,312吨,增长6%。
美国位居第二,出口量达102,947吨,增长8%。
表现出强劲增长的市场包括:以色列(+28%)、加拿大(+26%)、西班牙(+16%)和澳大利亚(+4%)。
中东市场大幅萎缩,其中阿联酋暴跌79%,沙特阿拉伯下降28%。
生腰果进口
2026年前8个月,越南进口RCN 212万吨,同比2025年下降2.29%。
受平均进口价格升至1,658美元/吨(同比上涨8.17%)拉动,进口总额增长5.69%。
按来源国划分的RCN进口量
- 柬埔寨:101.7万吨,增长约10%,占进口总量的近一半。
- 科特迪瓦:360,105吨,下降10.18%。
- 尼日利亚:164,706吨,下降21.85%。
- 坦桑尼亚:165,352吨,增长23%,成为非洲国家中增长最快的供应国。
- 加纳:115,675吨,大幅下降。
4. 国际腰果仁价格
参考FOB价格(截至2026年9月14日)
| 规格 | 越南(美元/磅) | 非洲(美元/磅) |
| W240 | 3.52 | 3.73 |
| W320 | 3.20 | 3.48 |
| WS | 2.67 | 2.73 |
| LP | 2.07 | 2.33 |
5. 短期展望
由于买家尚未接受当前价格水平,腰果仁市场近期可能继续保持缓慢交易状态。
高企的RCN成本仍是重要支撑因素,使得腰果仁价格难以大幅下跌。
自10月19日开启的坦桑尼亚2026/27季作物拍卖将成为导向2026年第四季度RCN市场走势的关键因素。
坦桑尼亚和莫桑比克目前天气良好,但9月底至10月初的阶段对坐果率及最终产量至关重要。
在印度,卢比走弱和高昂的RCN成本将在短期内继续限制腰果仁价格的下行压力。
预计未来几周腰果仁价格将维持稳定,但若缺乏主要消费市场的强劲新需求,难以出现突破性行情。
综合来源与免责声明
*免責聲明:本简报仅供参考,不构成投资建议或交易咨询。数据、观点及预测汇编自发布时被认为可靠的来源,但不保证其准确性、完整性或及时性。发布方不对因使用本简报信息而产生的任何损失承担责任。请在做出决策前审慎考虑并咨询专业人士。